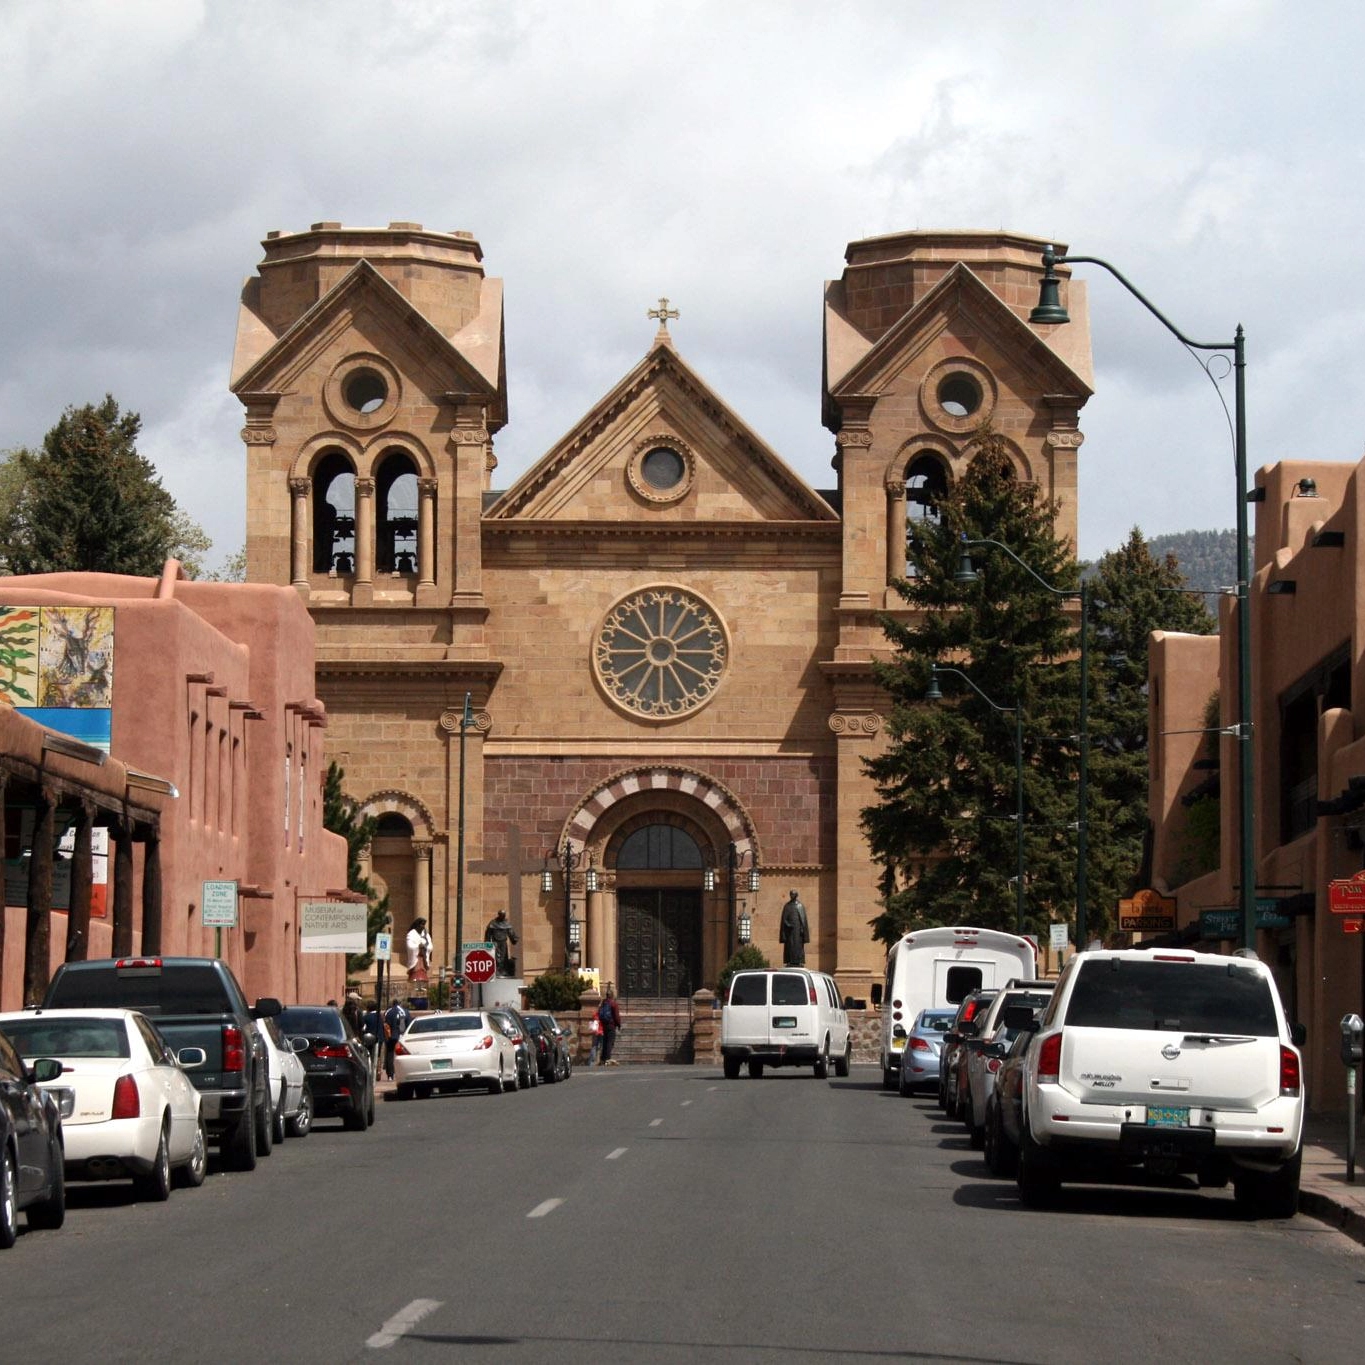
Airbnb and Short-Term Rental Financing in New Mexico
Short-term rentals can earn more than a traditional lease, but they are harder to finance. Income moves with the seasons, bookings come from a platform instead of a signed 12-month lease, and not every lender is comfortable with that. Some will count nightly income. Some won’t count it at all.
Brokers de Santa Fe helps investors across Santa Fe and northern New Mexico by finding lenders whose rules actually fit a short-term rental.
Why STR Financing Is Different
With a long-term rental, the lender looks at a lease or a market rent estimate and moves on. With a short-term rental, it has to decide what income is realistic. That leads to a few differences:
- Lenders may require a 12-month booking history, or accept a third-party revenue projection for new properties
- Higher insurance costs for short-term rental coverage are factored into the payment
- Furnishing, cleaning and management costs may be considered
- Condos and HOA communities face extra review because many restrict nightly rentals
- Rural and resort-area properties can have fewer comparable sales for the appraiser
Loan Options
Financing Options for Short-Term Rentals
DSCR loans for Airbnb properties
The most common route. The lender compares STR income to the monthly payment. Depending on the program, income may come from your actual booking statements, a projection from a rental data provider, or the appraiser’s long-term rent estimate. No tax returns are needed, and the loan can often close in an LLC. Learn more on our no income verification investment loans page.
Conventional investment property loans
If you already report STR income on your tax returns, a conventional investment loan may qualify you using that history. Pricing can be better, but documentation is stricter.
Cash-out refinance on an existing STR
Already running a successful Airbnb? A cash-out refinance can turn that equity into the down payment for another property. Lenders usually prefer to see a solid track record of bookings. See our cash-out refinance for investment property guide for how LTV and seasoning work.
A word on second-home loans
Second-home loans carry lower down payments, which makes them tempting. They are meant for properties you use personally, and they come with occupancy and rental restrictions. Using one to buy what is really a full-time rental can create serious problems. We’ll help you choose the loan type that matches how you plan to use the property.
New Mexico is generally friendly to short-term rentals at the state level, but local and private rules still apply. Before you make an offer, it’s worth confirming a few things:
- HOA and CC&Rs. State law does not override private deed restrictions. Many HOA communities restrict or prohibit short-term rentals, so read the CC&Rs before buying.
Rules change, so verify the current requirements for your specific address. We’re not attorneys, and this is general information, not legal advice.
Santa Fe & Northern New Mexico STR Markets We Work In
- Santa Fe. Demand comes from the Santa Fe Opera, Indian Market, Spanish Market, Canyon Road galleries, the Railyard and ski season at Ski Santa Fe.
- Taos. Taos Ski Valley, Taos Pueblo and the arts scene bring visitors all year.
- Los Alamos and White Rock. Lab staff, contractors and interns create steady demand for furnished mid-term stays.
- Rural northern New Mexico (Pecos, Abiquiú, Ojo Caliente, Madrid and Cerrillos). Cabins, homes on acreage and manufactured homes on land can work, but lender options narrow, which is where broad lender access helps.
What to Have Ready
- Property address and purchase price or estimated value
- Booking history or revenue reports from Airbnb or VRBO (for existing STRs)
- Details on HOA, taxes and insurance
- Proof of down payment and reserves
- Entity documents if closing in an LLC
Why Investors Use a Broker for STR Loans
Short-term rental lending varies more from lender to lender than almost any other investor product. One may cap the loan at a lower amount on a condo, another may not accept projected income, a third may treat your property’s history favorably. Because Brokers de Santa Fe, a brokerage brand of Federal First Lending LLC, works with many wholesale lenders, we can compare them for your exact property and explain the trade-offs, including prepayment terms. For every investor option, visit our investor cash-out hub.
CLIENT TESTIMONIALS
Real People. Real Journeys.
From first homes to second properties and investment opportunities, our clients value clear communication, local knowledge, and financing options that fit their situation.
We were buying a second home in Santa Fe and had a lot of questions about the property and financing. The Brokers de Santa Fe team explained everything clearly and kept us informed from application through closing.
FREQUENTLY ASKED QUESTIONS
Airbnb and Short-Term Rental Financing
Yes, with some lenders. They may use a third-party revenue projection or the appraiser's long-term rent estimate. Expect more conservative terms than on a property with a proven booking record.
Many DSCR lenders will, using booking statements or a projection. Conventional lenders typically rely on income reported on your tax returns.
Yes. Lenders usually want to see a track record of bookings and enough equity in the property.
FHA and VA loans are for properties you live in. Renting out a room or other units in a home you occupy may be possible within program rules, but these loans are not designed for dedicated vacation rentals.
Talk to Us About Your Rental
Whether you’re buying your first STR or refinancing your third, call (505) 369-5285 or use the form below. We’ll review the property and tell you which programs are realistic, subject to program availability and qualification.